Educational Blogs
Schedule a Meeting With Brian Cannon or Call 877-346-7567
“Third-Party Posts”
The following link/content may include information and statistical data obtained from and/or prepared by thirdparty sources that Wealth Personal, deems reliable but in no way does Wealth Personal guarantee its accuracy or completeness. Wealth Personal had no involvement in the creation of the content and did not make any revisions to such content. All such third-party information and statistical data contained herein is subject to change without notice and may not reflect the view or opinions of Wealth Personal. Nothing herein constitutes investment, legal or tax advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of Wealth Personal, execution of required documentation, and receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results.
The Hidden Risk of “Waiting Too Long” to Get Your Financial House in Order
Most people do not ignore their finances because they do not care.They ignore them because life gets busy. Work takes over. Family needs attention. Retirement feels far away. Insurance paperwork feels confusing. Estate planning gets pushed to “later.” Before long,...
What Inflation Is Quietly Doing to Your Retirement Plan
When most people think about retirement planning, they focus on the big numbers. How much they have saved. How much income they will need. When they want to retire. But there is one factor that quietly works in the background year after year, and if it is not...
Last-Minute Tax Moves Before April 15: IRA, HSA, and Retirement Planning Tips
As April 15 approaches, many people assume the window for tax planning has already closed. The truth is, there may still be time to make a few smart financial moves that could help reduce taxable income, strengthen retirement savings, and improve long-term financial...
Building a Stronger Financial Future with the Right Guidance
When it comes to your financial future, confidence does not come from guessing. It comes from having a clear strategy, trusted guidance, and a plan built around your goals. Whether you are preparing for retirement, protecting your family, growing your wealth, or...
Why Financial and Insurance Planning Should Work Together
When people think about financial planning, they often focus on investments, retirement accounts, and growing wealth. When they think about insurance, they usually think about protecting their home, health, or family. The truth is, these two areas should never be...
Understanding Annuities: Turning Retirement Savings Into Reliable Income
Planning for retirement has changed dramatically over the past few decades. In the past, many retirees relied on pensions and Social Security to provide dependable income throughout retirement. Today, pensions have largely disappeared, leaving many retirees...
The Retirement Wildcard: How Healthcare Costs Can Impact Your Financial Future
When most people think about retirement planning, they focus on the obvious questions: Will my savings last? How much income will I need? When should I take Social Security? But there’s one major expense that often catches retirees off guard. Healthcare. In fact,...
The Retirement Income Plan Most People Think They Have — But Don’t
Retirement isn’t about how much you’ve saved. It’s about how you turn your savings into income you can rely on — for 20, 30, or even 40 years. Most people believe their 401(k), IRA, or brokerage account is their retirement plan.But an investment account is not an...

Weekly Market Commentary
Weekly Market Commentary
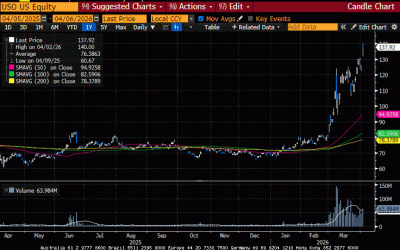
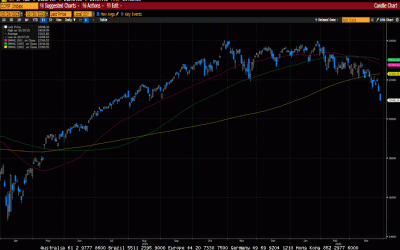
US markets fell for the fourth consecutive week as the US-Israel-Iran conflict entered its 5th week. President Trump’s announcement that he would extend the deadline to reopen the Strait of Hormuz by a couple of days sent markets soaring on Monday, but gains were met...
Weekly Market Commentary
US markets fell for a third consecutive week as investors continued to assess the implications of the Iran conflict. Headlines related to Iran continued to dominate market attention. Energy markets traded higher as the military's focus shifted to energy...
Weekly Market Commentary
Markets remained volatile, driven by headlines related to the Iran war. Whipsaw action was prominent across multiple asset classes, while several historically safe-haven assets offered no cover for investors. Questions about the duration of the war and the closure...
Weekly Market Commentary
Investors endured a difficult week as the conflict between the US, Israel, and Iran continued. Iran’s efforts to target US military bases in the region broaden the conflict across the Middle East. Energy shipments through the Strait of Hormuz have come to a...
Weekly Market Commentary
US equity markets regressed as several themes that have propelled the market higher over the last couple of years have had to be reassessed. Return on investment from AI capex, a Federal Reserve on hold, tariff uncertainty, and increased geopolitical tensions have...
Weekly Market Commentary
The holiday-shortened week produced gains across US indices and saw an emerging market ETF break out to all-time highs. The start of the Chinese Lunar New Year and Ramadan tempered international trading volumes. The tail end of Q4 earnings continued to show...
Weekly Market Commentary
US financial markets regressed in choppy trade. The narrative around the disruptive nature of AI continued to impact markets. Rotation away from growth and mega-cap issues continued while proceeds flowed to defensive sectors and small caps. Interest rate-sensitive...
Weekly Market Commentary
Investors endured a volatile week on Wall Street as 4th quarter earnings continued to roll in. Concerns about massive capital expenditures resurfaced after Amazon and Google announced $200 billion and $185 billion in capex, respectively. This comes after last week’s...

Ed Slott’s Elite IRA Advisor Group (Ed Slott Group) is a membership organization owned by Ed Slott and Company, LLC. Logos and/or trademarks are property of their respective owners and no endorsement of (Wealth Personal) is stated or implied. Ed Slott Group and Ed Slott and Company, LLC are not affiliated with Wealth Personal.
For the detailed requirements of Ed Slott’s Elite IRA Advisor Group, please visit: https://www.irahelp.com/
The Look-Through Rules for Trusts
By Sarah Brenner, JD Director of Retirement Education The SECURE Act, the SECURE 2.0 Act, and subsequent regulations have brought us a complex set of rules for IRA beneficiaries, including trusts. Only individuals who are named on the IRA beneficiary form (or named...
The Roth Conversion Transaction Custodians Dislike
By Andy Ives, CFP®, AIF® IRA Analyst Anyone with a traditional IRA can do a Roth conversion. As long as the funds are eligible to be rolled over, they can be converted. With a Roth conversion, traditional IRA funds are moved into a Roth IRA. This movement of funds is...
Does the Secure Act’s 10-Year Rule Apply to Inherited Roth IRAs?: Today’s Slott Report Mailbag
By Sarah Brenner, JD Director of Retirement Education QUESTION: Does the SECURE Act’s 10-year rule apply to inherited Roth IRAs? ANSWER: Yes, the SECURE Act’s 10-year rule also applies to inherited Roth IRAs for non-eligible designated beneficiaries (NEDBs). That...
Creditor Protection for Your Retirement Accounts
By Ian Berger, JD IRA Analyst How well are your retirement plan account funds protected from creditors? The answer depends on which kind of creditors you are worried about. There are two types of creditors that might be coming after your retirement savings. The first...
How Your Spouse Can Impact Your Traditional IRA Deduction
By Sarah Brenner, JD Director of Retirement Education If you have compensation (or “earned income”), you can always contribute to a traditional IRA, but your traditional IRA contribution may not always be deductible. (Roth IRA contributions are never deductible.) One...
Is there a penalty because the RMD was not taken prior to Mom’s passing?: Today’s Slott Report Mailbag
By Andy Ives, CFP®, AIF® IRA Analyst QUESTION: You recently posted an article about the “still-working exception.” Does this apply to solo 401(k) plans? Thanks, Birdie ANSWER: Birdie, The still-working exception allows participants in certain workplace retirement...
530A Trump Accounts: The Compounding Mathematical Facts
By Andy Ives, CFP®, AIF® IRA Analyst These days, anything with a hint of politics can be divisive. Trump accounts are no different. Public comments about this new savings vehicle are clearly rooted in the political divide that permeates our country. We are all sick up...
Not Child’s Play: How the “Kiddie Tax” Works
By Ian Berger, JD IRA Analyst With contributions to Trump accounts having gone live on July 4, 2026, there has been lots of discussion recently about the “kiddie tax.” That’s because, once a child reaches January 1 of the year they turn age 18, they will be able to...
Does the Five-Year Holding Period Pertain to Me?: Today’s Slott Report Mailbag
By Ian Berger, JD IRA Analyst QUESTION: My wife (Keiko) currently does not take a required minimum distribution (RMD) on her retirement account because the plan allows this while she is still working. Here are our questions: If she retires this December (2026), would...
Find a Wealth Personal Location
Elk Rapids, Michigan
212 River Street
Elk Rapids, MI 49629
Office: 877-346-7567
Fax: 231-264-8488561-329-2650
brian.cannon@wealthpersonal.com